

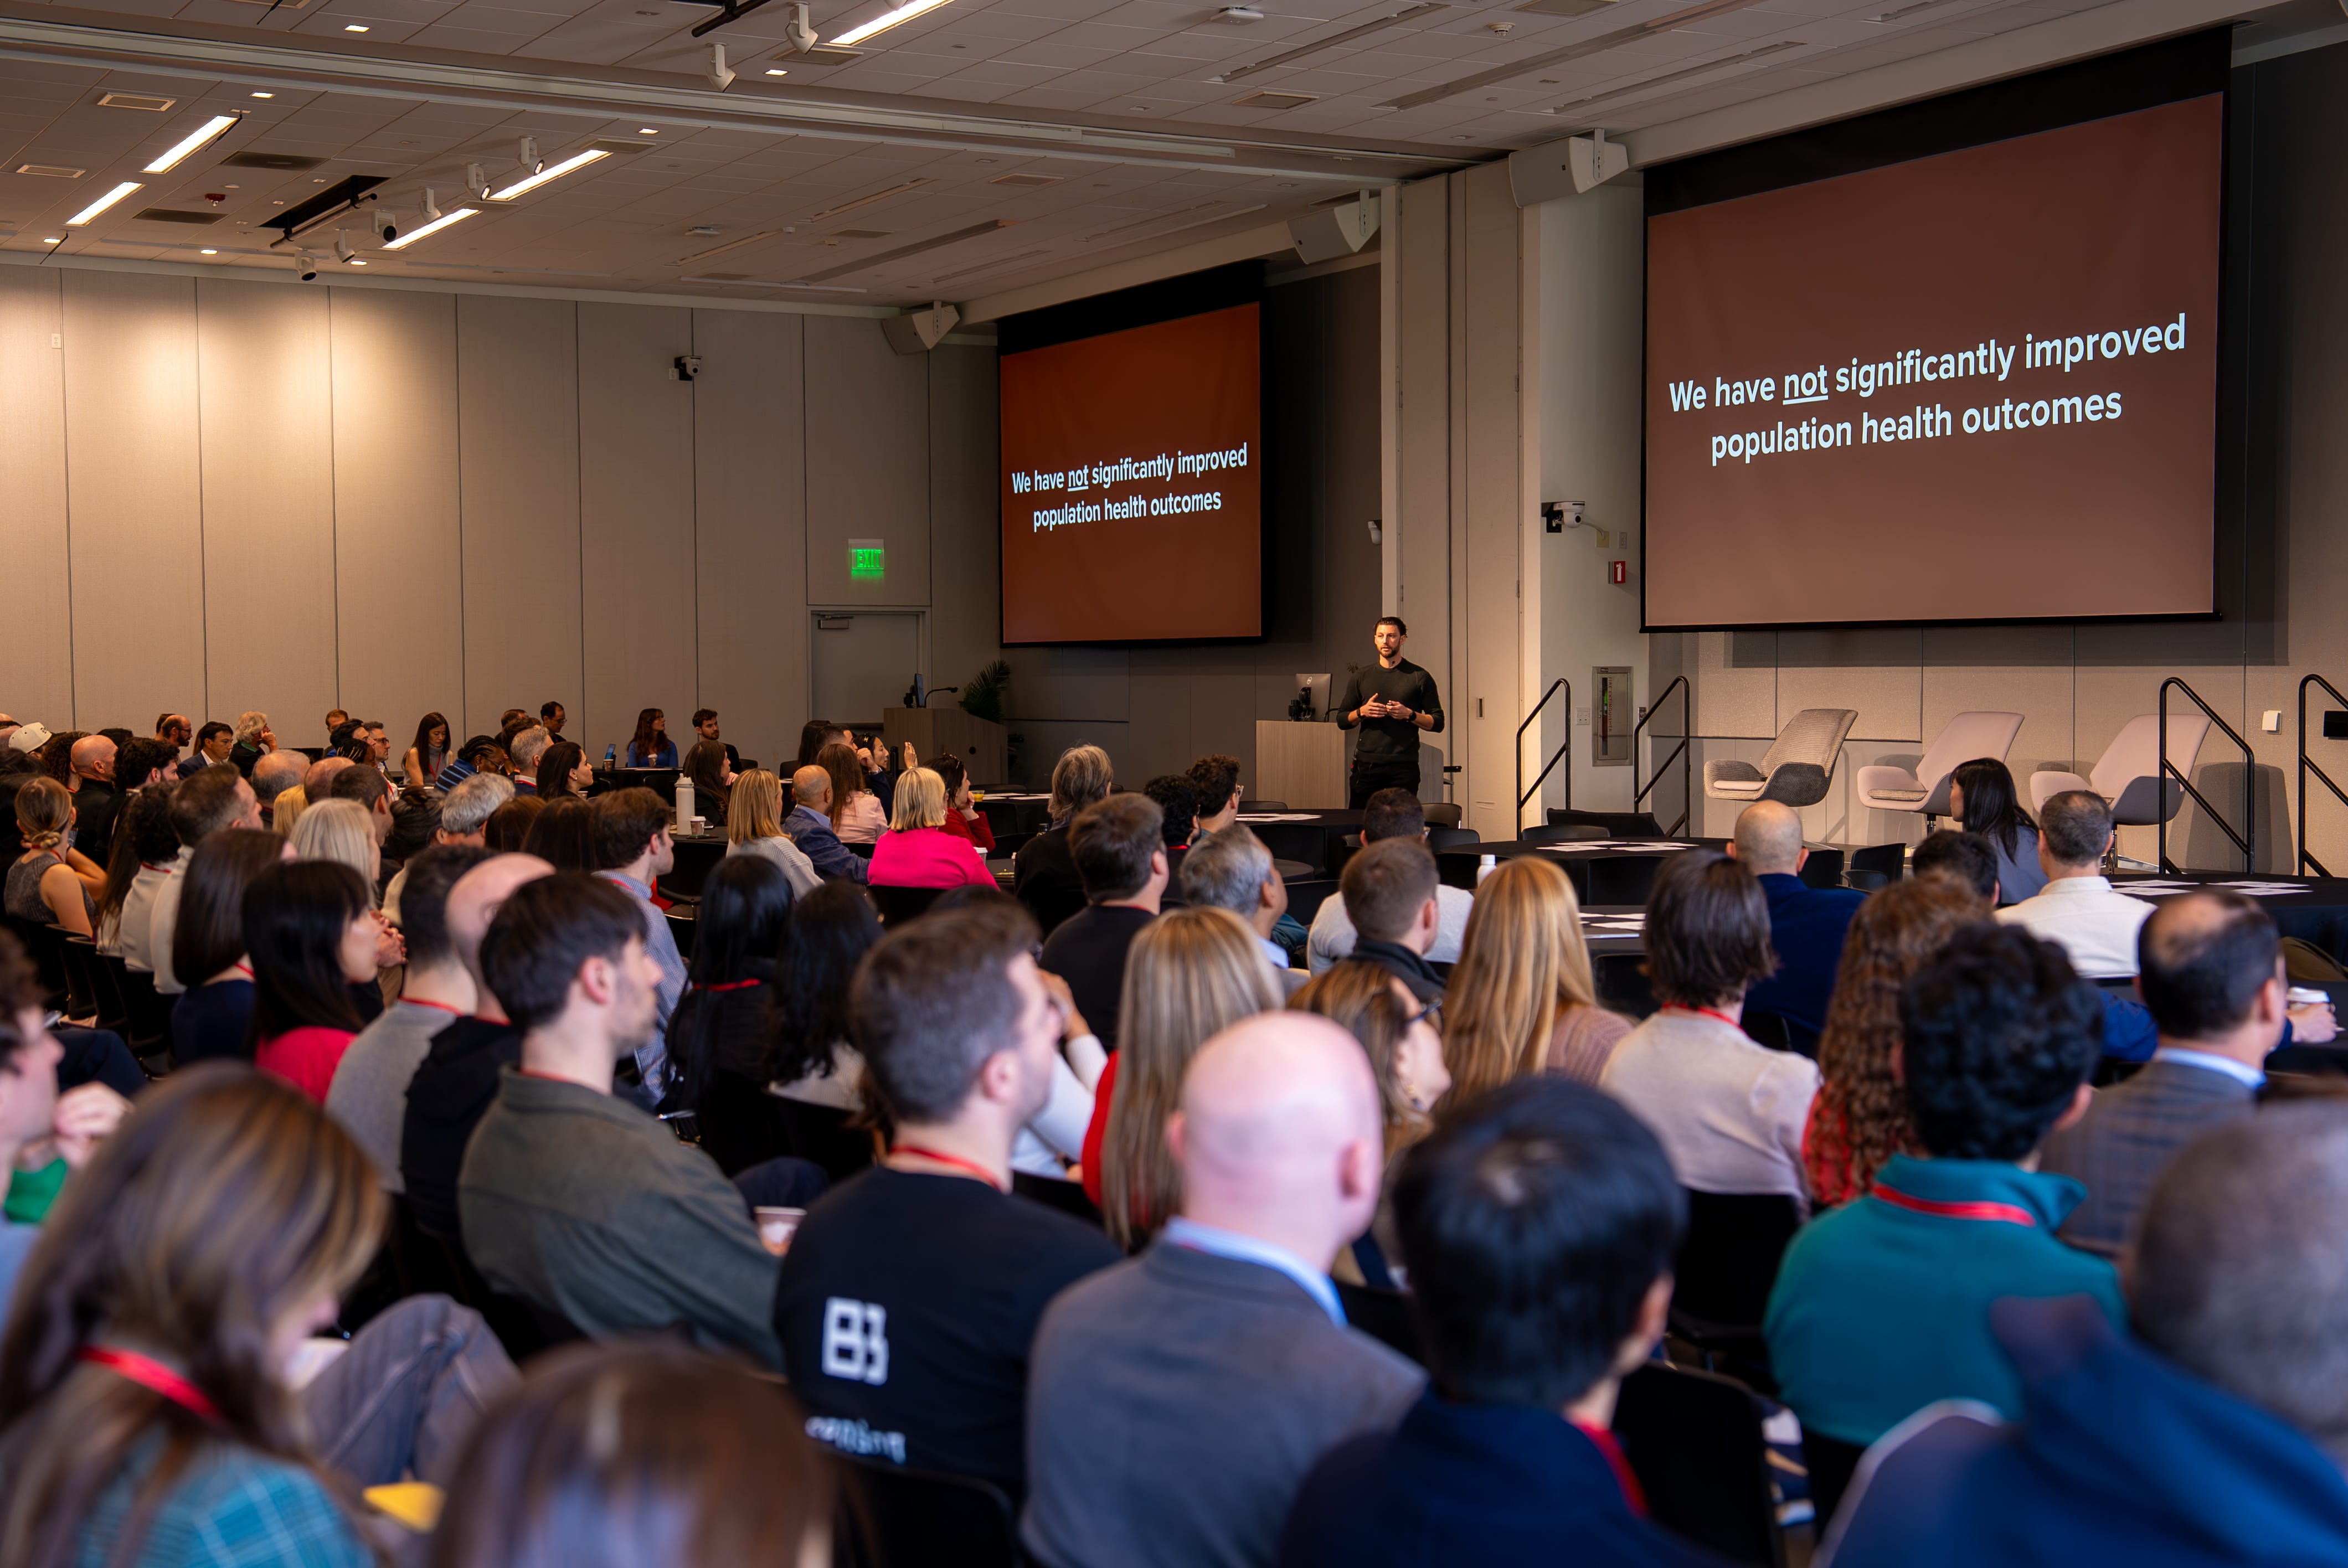
In February 2026, more than 400 people packed into Li Ka Shing at Stanford Medicine for a one-day summit centered on a single question: What does the next decade of consumer-empowered care look like, and who are the companies driving it?
Eight months earlier, the conference didn’t exist. It started as an idea as I spent a summer interviewing founders, mapping the consumer health industry, and becoming increasingly convinced that there was a gap no one was filling. There were conferences focused on healthcare research. There were conferences about AI in medicine. But there wasn’t a gathering that brought together students, founders, investors, and scientists to discuss how to actually build scalable businesses that improve health outcomes. That was the niche.
Getting it off the ground required 50 emails to find one faculty sponsor, 180 outreach attempts to secure 10 sponsors, and more moments of doubt than I’d care to admit. I almost didn’t take the call with the faculty member who eventually said yes — because twelve had already said no.
But it happened. And the response far exceeded anything I anticipated.
By the numbers
We sold out twice — first at 400 tickets, then again at 475 when we added an overflow room. VIP tickets sold out in under 24 hours. All 400 general tickets were gone within the first week. The waitlist topped 400 people. The interest list topped 1300 people. Over 250 attendees stayed the entire day — more than eight hours.
The speaker lineup included 30+ CEOs, VPs, investors, and entrepreneurs representing companies with a combined valuation north of $20 billion: WHOOP, Oura, HYROX, Headspace, Noom, [solidcore], Function Health, Midi Health, Eight Sleep, Eudemonia, and others. Forbes, TechCrunch, The New York Times Wirecutter, The Washington Post, CNET, The Wall Street Journal, and Business Insider all expressed interest in covering the event.
Top-line revenue was $150K, raised in under seven months through sponsorships and ticket sales. Over 500K impressions were generated on LinkedIn from posts by attendees, speakers, and sponsors in the weeks leading up to and following the event.
A deeper undertone ran throughout the day: the consumer health movement has not yet meaningfully shifted key U.S. health indicators, including obesity and depression. To date, the industry has largely served higher-income, informed, motivated, and generally healthy individuals — understandable given its early-adopter stage. I opened the day with that reality as a call to action, asking speakers and attendees to name what must be true for this space to deliver not only financial returns, but real systemic health impact.
What followed was one of the most substantive days of conversation I’ve been part of. Below are the themes that defined it.
Theme 1: Trust and evidence are the real competitive moats
This was the through-line of nearly every session. Not trust as a branding exercise — trust as a business strategy.
Ricky Bloomfield, CMO of Oura, was direct: if consumer health platforms want to be taken seriously, they must measure clinical outcomes and healthcare cost reduction, not just engagement metrics. Alex Vannoni from WHOOP described trust as the result of seeing real results and outcomes, which leads to sustained engagement. Creating “magical moments” through high-fidelity health data builds the confidence that keeps people in the product.
Christopher Gardner, Stanford professor of medicine, put it most starkly: “The tech is ahead of the science, and the science is trying to catch up. If we don’t have the science to back up the products, they will never be complete, and people will be distrustful.”
The companies investing in clinical rigor now — funding trials, building medical advisory boards, pursuing FDA engagement — are not doing it to check a box. Oura, WHOOP, Noom, Eight Sleep, and January AI are all running real-world evidence programs. Geoff Cook shared that Noom will invest $10 million in research in 2026 alone. Science is becoming the moat that marketing cannot replicate. And for an industry where NAD, trending supplement protocols, and heavily marketed longevity products are running ahead of peer-reviewed validation, that matters.
Theme 2: The shift from reactive to proactive is happening — but the barriers aren’t technological
The clearest macro theme across sessions: care is moving from episodic, hospital-centered treatment to continuous, consumer-controlled prevention. One stat captured it perfectly — 97% of the $5.3 trillion U.S. healthcare spend goes toward treating disease. Only 3% goes to prevention. We have built an almost perfectly reactive system.
Multiple panels reinforced that wearables are becoming core clinical infrastructure rather than optional accessories. Oura and WHOOP are actively pursuing FDA-recognized clinical outcomes. CGMs, HRV, sleep data, and metabolic markers are evolving into data streams that may one day replace some of what currently requires a clinic visit. WHOOP reports that roughly 70% of monthly users check the app every single day — that’s not a gadget; that’s behavior-change infrastructure.
But the biggest barriers to this future are not technological. The tech largely exists. The hard problems are getting people to change their behaviors and making these tools accessible and affordable beyond an affluent early-adopter segment. As one attendee wrote afterward: “Consumer health is still largely inaccessible. How might we bring a stronger lens of moral obligation around access?”
Theme 3: Data is abundant — meaning is scarce, and AI changes the economics
“Data is the marketing for medicine,” said Geoff Cook.
Wearables, CGMs, at-home diagnostics, sleep trackers, and continuous biomarkers are generating more signal than ever. The bottleneck is no longer data collection — it’s translation. Matteo Franceschetti of Eight Sleep said it directly: users don’t want to learn multiple apps. They want to understand what matters to them. In the near future, that means a personal health agent that doesn’t just collect data but knows your context, maintains continuity, and routes you to the right intervention at the right moment.
There was lively discussion about a personal operating system for health — a unified environment consolidating wearables, biomarkers, and AI-driven insights. But as multiple investors pointed out, blending data across wearables, sleep devices, CGMs, EMRs, and nutrition logs is far more complex than marketing suggests. Fragmentation is not disappearing. The opportunity may not be the aggregator, but the infrastructure layer that makes aggregation usable.
Alison Ryu of Able Partners framed the AI opportunity clearly: it’s not the AI doctor. It’s the orchestration layer. And on the economics side, she made the point that AI has finally made it possible to build a counterfactual at the individual level — to put a dollar value on the health outcome that didn’t happen. That changes the ROI case for prevention in a way that a self-insured employer or payer will actually act on.
Theme 4: How investors and builders are thinking about the next chapter
The investor panel — Julie Yoo (a16z), Holly Maloney (General Catalyst), Alison Ryu (Able Partners), and Kurt Seidensticker (Starshot Ventures) — delivered a sharp message: they want retention that tells a behavioral story. The companies that struggle are the ones where cancellation costs the user nothing, because the product never became part of their life. The companies that win are the ones where leaving means giving up a result, an insight, a community, or an identity.
GLP-1s emerged as a case study in this dynamic. Geoff Cook’s framing was one of the most-discussed ideas of the day: 11 out of 12 people stop taking GLP-1 medications by year 3, and without lifestyle change, the weight comes back. A full third of people signing up for Noom were previously on a GLP-1. The medication opens a window. What you build inside that window — habits, routines, identity — is what determines whether the change lasts. The behavior change infrastructure is the product.
Community surfaced as an unexpected through-line. Jonathan Leary, CEO of Remedy Place, described the paradox: “The healthier I got my patients, the more isolating their lifestyle became. That’s where the birth of social self-care was.” Companies like HYROX, [solidcore], and Eudemonia aren’t in the fitness business — they’re in the belonging business, making the healthy behavior the social behavior. Shared discomfort builds bonds, and bonds drive retention.
What’s coming in this series
This write-up is the first in a four-part series. Over the next three weeks, I’ll go deeper:
Part 1: How a second-year MBA built a 400-person conference from scratch. The origin story — from the idea through the rejections, the breakthroughs, the viral LinkedIn post, and the moments of doubt that almost ended it before it started.
Part 2: What the industry’s best told us about the next decade of consumer health. A deeper dive into the panels, the quotes, and the open questions the conference surfaced — with my own take on what it means.
Part 3: The playbook. A step-by-step guide to building a conference from zero: finding sponsors, securing speakers, selling out tickets, and the lessons I took away about building something from nothing.
If you’re interested in the future of consumer health — as a founder, investor, operator, or someone who simply cares about living better — I hope this series is useful. And if you’re interested in attending or getting involved in next year’s event, you can sign up here: https://forms.gle/tBqzqdGgdrW9qEtj9
Thank you to everyone who helped bring this conference to life — our sponsors, speakers, faculty, volunteers, and attendees. My hope is that this jumpstarts an ongoing conversation at Stanford and beyond about financially viable solutions that improve health outcomes while positively transforming the medical system. We need that now more than ever.
so incredible, zach! it's true...we have an overwhelming amount of data, but companies need to figure out how to support people in converting that into action and behavioral change. hope to be involved next year.